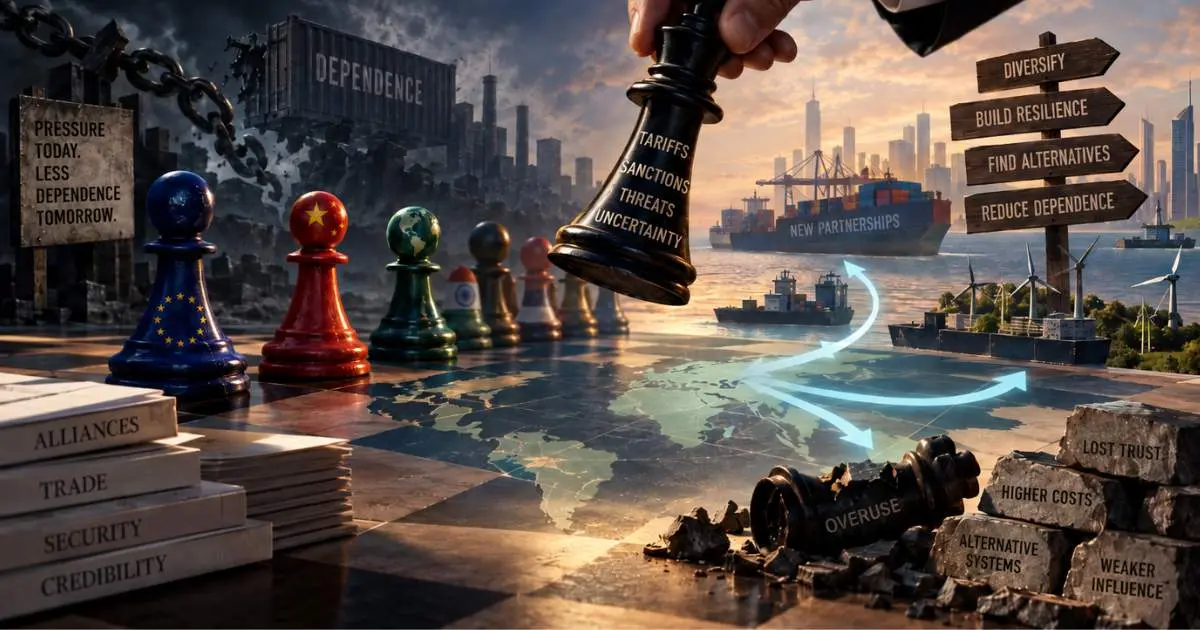
Unpredictability can make threats more powerful, but it can also make promises less valuable. When governments repeatedly use uncertainty to extract concessions, allies and adversaries begin protecting themselves against the relationship itself. The result is a paradox of power: pressure may succeed today while teaching others how to become less vulnerable tomorrow.
There is a seductive logic behind unpredictability in foreign policy. If another government cannot tell whether you will raise a tariff, withdraw troops, widen a demand, strike militarily or suddenly accept a deal, it must prepare for several futures at once. Preparation is expensive. Companies delay investment, ministries draft contingency plans, allies spend money on capabilities they might otherwise have postponed, and negotiators may offer concessions simply to remove the worst possibility from the table. Uncertainty, in other words, can impose costs before the threatened action ever occurs.
That makes unpredictability potentially useful. It does not, however, make it free. The government that repeatedly forces others to insure themselves against its next move eventually confronts the consequences of that insurance: alternative suppliers, larger defence budgets, new trading partners, redundant payment systems, domestic industrial capacity and political coalitions designed to reduce exposure to future pressure. What looks like leverage in the immediate negotiation can become an instruction manual for escaping that leverage later.
There is an even more fundamental problem. Coercion cannot work through fear alone. The target must believe not only that resistance will hurt, but that compliance offers a credible route out of the pain. If the demand keeps moving, if concessions invite new demands, or if yesterday’s agreement provides no confidence about tomorrow’s pressure, refusing to concede can become rational even against a much stronger state. Unpredictability then stops increasing bargaining power and begins destroying the conditional logic that makes coercion possible.
The distinction is easy to miss because several different ideas are often placed under the same label. Strategic ambiguity, calculated risk, brinkmanship, policy volatility and simple incoherence can all make another government uncertain, but they do not work in the same way. The difference between them is the difference between uncertainty that structures another actor’s choices and uncertainty that merely makes those choices harder to understand.
Strategic Ambiguity Is Not Strategic Unpredictability
The classic example of strategic ambiguity is the United States’ posture toward Taiwan. Washington has historically declined to state with complete certainty whether American forces would intervene if China attacked Taiwan. The ambiguity was not supposed to make every dimension of American policy unknowable. Its logic was narrower: Beijing should not be confident that aggression would avoid American intervention, while Taipei should not be confident that unilateral moves toward formal independence would automatically receive American military protection. It was an attempt at dual restraint, not a doctrine of permanent surprise.
Whether that policy remains stabilising is now contested. Some American analysts argue that China’s increased military capabilities have made ambiguity more dangerous because Beijing could interpret uncertainty about US intervention as weakness; others continue to see value in preserving flexibility and restraining both sides. The disagreement itself illustrates the point: strategic ambiguity is a calibrated policy about what should remain uncertain and why. It can be assessed against an identifiable objective—deterrence and restraint in the Taiwan Strait.
Strategic unpredictability is broader. The target may be uncertain not merely about whether a threatened action will occur, but about the demand, the timetable, the instrument being used, the duration of punishment and whether an agreement reached today will survive tomorrow. When several of those variables move at once, the purpose of uncertainty changes. It no longer simply preserves freedom of action; it can become a means of forcing the other side to absorb the cost of preparing for outcomes that have not yet been chosen.
The idea itself is not new. Thomas Schelling famously analysed coercion through threats that deliberately leave some outcome to chance, while Richard Nixon sought to cultivate a reputation for dangerous unpredictability during the Vietnam era. Yet the historical record also cautions against assuming that appearing unpredictable automatically strengthens a coercer. Scholarship on Nixon’s “madman” strategy finds that attempts to manipulate perceptions could harden resistance or be interpreted as calculated theatre, while broader research suggests that a reputation for irrationality can sometimes help in crisis bargaining but can also damage deterrence.
The useful question is therefore not whether unpredictability is inherently good or bad, but what kind of uncertainty is being created, who pays for it, and whether the behaviour it produces strengthens the coercer beyond the immediate negotiation.
The Cost Starts Before the Threat Is Carried Out
A tariff does not have to take effect to change behaviour. A troop withdrawal does not have to occur to alter allied defence planning. A sanctions package does not have to be signed before banks begin reviewing exposure. Once a sufficiently consequential policy becomes plausible, governments and businesses begin paying for the possibility.
Economic research makes this effect unusually visible. The Federal Reserve has documented how trade-policy uncertainty can delay investment, foreign-market expansion and hiring even when firms do not yet know what tariff will ultimately apply. In June 2026, Fed researchers noted that the sharp rise in US tariffs during 2025 contributed to record-high trade and economic-policy uncertainty and warned that ambiguity over the duration and severity of tariffs could itself work against the goal of attracting investment into the United States. The same study found that aggregate foreign direct investment had nevertheless remained relatively resilient in 2025, demonstrating that the costs of uncertainty need not appear as an immediate economy-wide collapse in investment.
An IMF working paper examining the 2025 trade-policy shocks likewise found that corporate valuations were affected through both direct trade exposure and a separate uncertainty channel, with the two effects jointly accounting for a significant share of market reactions. These findings help explain why the consequences of a threatened policy cannot be measured simply by looking at what was eventually implemented.
This is an important difference between pressure and punishment. Punishment imposes a known cost after an action is taken. Uncertainty makes the target decide how much to spend protecting itself against a range of possible costs. A company that cannot estimate its future tariff rate may postpone a factory. A government unsure about the durability of a security commitment may increase defence spending earlier than planned. A supplier fearing future export controls may duplicate production across jurisdictions even if the restriction never arrives.
The resulting cost can therefore exceed the policy actually implemented. The target is purchasing insurance against the threatener’s range of possible actions, and insurance is rarely free. This was one of the problems visible during the trade-policy volatility that began in 2025: firms responded not simply to tariff levels but to the possibility that announced rates, exemptions, legal authorities and bilateral agreements could change again. OECD assessments similarly concluded that persistent policy uncertainty was weighing on trade and investment alongside the tariffs themselves.
There is real leverage in this. A government that can make another actor spend money merely by leaving an option open possesses a form of power. But the mechanism contains the seed of its own limitation, because the rational response to repeatedly expensive uncertainty is to search for ways to become less exposed to it.
Pressure Before the Demand
Traditional diplomatic imagery places negotiation before escalation: governments define positions, bargain privately, threaten consequences and, if the bargaining fails, impose them. Contemporary coercive diplomacy increasingly scrambles that sequence. The threat may appear publicly before the demand has fully stabilised, or a trade measure may be announced while governments are still trying to determine what concession would remove it.
Tariffs have become especially useful for this purpose because they can cross policy domains. In 2025, the Trump administration explicitly linked tariffs on Canada and Mexico to fentanyl trafficking and, in Mexico’s case, border security rather than treating them solely as responses to trade imbalances. In January 2026, Trump threatened increasing tariffs on several European allies until the United States was allowed to buy Greenland. At the NATO summit in Ankara that July, he publicly ordered a halt to trade with Spain amid disputes over defence spending and Spain’s refusal to support US military action against Iran, even though an earlier attempt to pressure Spain through trade threats had not stopped bilateral commerce.
These episodes should not all be treated as equivalent, and a presidential announcement is not the same thing as an executable policy. Domestic law, courts, the European Union’s common trade policy and the practical interdependence of supply chains can constrain what a leader can actually do. That gap between announced pressure and implementable pressure is itself part of the bargaining environment: counterparts have to judge which threats are signals, which are opening bids and which will become policy.
Publicity changes the calculation further. Research on crisis bargaining suggests that public threats can be perceived as somewhat more credible than private ones because leaders may pay political or reputational costs for backing down. But the same literature identifies a second effect: public demands can increase the political cost of concession for the target as well. A private compromise can be described domestically as negotiation; capitulation after a public humiliation may be much harder to sell.
Public coercion therefore has a double edge. Going public can strengthen pressure by showing resolve and mobilising audiences, yet it can simultaneously remove the quiet bargaining space in which the other side might have conceded. The louder the threat becomes, the more the dispute can cease to be only about the original issue and become a contest over status, credibility and political survival.
Modern communications amplify that tension. A threat delivered in a press conference, social-media post or summit corridor reaches markets, voters, allies and opponents simultaneously. It can create immediate leverage precisely because no one can be sure whether it is theatre or instruction. It can also leave diplomats negotiating not only over substance but over the political consequences of words that have already travelled around the world.
Allies Pay a Different Price for Uncertainty
An adversary expects danger from you. An ally builds plans around the expectation that some dangers will be managed with you. That makes uncertainty inside an alliance qualitatively different from uncertainty between enemies. A rival confronted with an ambiguous threat asks what damage the threatener may inflict. An ally confronted with uncertainty over a security guarantee, troop presence or trade relationship has an additional problem: it may already have designed its own defence, industrial policy and diplomatic posture around the continuation of that relationship. What becomes uncertain is not merely the next action of another state but the value of previous decisions made in reliance upon it.
This does not mean alliances require perfect predictability. They never have. American presidents have disagreed with European governments over burden-sharing for decades, allies routinely dispute military interventions, and NATO was never a mechanism for eliminating national interests. Nor should Europe’s recent defence buildup be attributed simply to Donald Trump; Russia’s war against Ukraine, depleted weapons stocks and broader changes in the security environment are independent and powerful causes.
Yet uncertainty over American commitments now has concrete planning effects. In 2026 the Pentagon began a review of US troop deployments in Europe expected to produce several options for the roughly 80,000 American forces stationed across the continent. European allies sought clarity about whether the exercise represented consultation, strategic rebalancing or potential leverage over governments Washington considered insufficiently supportive. The eventual decision matters, but allied planning cannot wait for the answer.
The Greenland dispute created a different version of the same problem. European governments were not confronting an adversary threatening economic punishment but their principal security ally threatening tariffs in pursuit of control over territory belonging to the Kingdom of Denmark. The EU drew up possible retaliatory measures, including tariffs and the potential use of its Anti-Coercion Instrument, while simultaneously trying to prevent escalation. The episode did not dissolve NATO, but it forced Europeans to consider an uncomfortable category of risk: economic coercion coming from inside the strategic partnership on which much of their security architecture rests.
Allies have advantages that adversaries do not. They possess institutional channels, intelligence relationships, military interoperability, diplomatic access and mutual economic interests that make disputes easier to contain. Those channels are precisely why uncertainty among allies does not automatically become rupture, but they cannot fully remove the cost of planning around commitments whose durability has become a political question. An alliance is valuable partly because it reduces the number of futures for which every member must prepare alone; when the alliance itself becomes one of the uncertainties to insure against, some of that value is quietly spent.
When Unpredictability Works
It would be intellectually convenient to describe unpredictability as mere diplomatic recklessness, but it would also be wrong. Coercive strategies sometimes work precisely because the target cannot confidently dismiss the worst-case outcome, and Schelling’s insight remains useful here: bargaining power can arise from the manipulation of risk rather than from a simple promise to choose a specific action. The principle has appeared in nuclear brinkmanship, military crises and economic bargaining long before the current administration in Washington.
The Trump administration has also demonstrated that aggressive uncertainty can produce movement. Countries have entered tariff negotiations under the pressure of announced or threatened duties, and even Reuters’ critical assessment of Trump’s 2026 brinkmanship toward Iran noted that the same negotiating style had previously obtained concessions in some trade and conflict settings. At the July NATO summit, allies faced sharp public criticism before Trump switched to praise after welcoming increases in defence spending. None of these cases proves that unpredictability alone caused the outcome, because governments respond to material power, domestic interests and pre-existing strategic pressures as well. They do show why policymakers can become convinced that keeping counterparts off balance is useful.
The tactic is strongest under particular conditions. The coercer must possess real capacity to impose costs, the target must care enough about avoiding those costs, and the demand must leave some politically survivable way to comply. Dependence matters: threatening exclusion from a market is most powerful when the market is difficult to replace; questioning a security guarantee carries more weight when the ally cannot rapidly substitute another protector.
There is also value in not revealing every red line. Excessive clarity can teach an opponent exactly how far it can go without triggering a response, while uncertainty may make marginal aggression less attractive. A state does not need to publish a manual explaining every condition under which it will escalate. In some environments, carefully bounded ambiguity preserves flexibility and forces the other side to account for risks it cannot calculate precisely.
But the distinction between bounded uncertainty and moving uncertainty is crucial. In the first, the counterpart understands the underlying relationship even if it cannot know the exact response. In the second, the counterpart becomes unsure whether today’s concession will actually settle anything. That is where the strongest version of coercion encounters a problem that raw power alone cannot solve.
A Threat Needs an Exit
Most discussions of coercive diplomacy concentrate on the credibility of the threat. Will the coercer really impose the tariff? Will it actually strike? Is the military deployment serious? Does the government have the political will to absorb the costs of escalation? Those questions cover only half of the bargain, because the target must also believe that some form of compliance can actually change what happens next.
Research by Reid Pauly on what he calls coercive assurance identifies this second requirement clearly. A coercer does not merely need to communicate that resistance will cause pain; it must make credible that compliance can avoid or end that pain. Even a severe and believable threat can fail when the target concludes that punishment will arrive regardless of what it does.
The distinction transforms the logic of unpredictability. Imagine a government facing a much stronger state. If it believes that making one specified concession will remove a specified penalty, it can weigh the political cost of concession against the economic or military cost of resistance. The bargaining problem is harsh but intelligible. If it instead believes that the first concession will reveal weakness, produce a second demand, or fail to remove the threatened punishment, the calculation changes. Giving in no longer purchases safety; it purchases uncertainty at a worse bargaining position.
Moving demands are therefore not always a demonstration of strength. They can undermine the coercer’s own offer. The same is true when different officials appear to communicate different end states, when domestic actors can continue punishment after the executive has accepted a deal, or when a target has reason to suspect that the coercer’s actual objective is much broader than its declared demand.
The Iran crisis in 2026 illustrates the problem without providing a laboratory in which one explanation can be isolated from all others. Reuters reported in May that American coercive diplomacy had run into strong resistance amid public threats, maximalist demands, mixed signals and Iranian concerns about humiliation and further concessions. Analysts disagreed over responsibility for the stalemate, and Iranian leaders possessed their own ideological, strategic and domestic reasons to resist. Yet the episode demonstrates the bargaining difficulty identified by research on coercive assurance: a target that doubts whether concession will produce a stable end to pressure may rationally absorb extraordinary costs rather than concede.
Later negotiations illustrated the other side of the logic. Draft arrangements discussed in June linked specific Iranian steps, including reopening the Strait of Hormuz, to reciprocal measures such as easing restrictions, sanctions relief and access to frozen assets. Whatever the eventual fate of those negotiations, the structure was more legible because demands and relief were connected. Coercion becomes bargaining only when the target can see a path from compliance to a different outcome.
This is why a threat needs an exit. The target need not trust the coercer as a friend, and it need not know exactly how the coercer will behave if it refuses. It does, however, need some confidence that there exists a behaviour that will stop the punishment. Without that conditionality, the threat may remain frightening while becoming less useful.
When Unpredictability Stops Being Strategy
Uncertainty is strategically useful when it changes incentives in a direction the coercer understands. It becomes strategic noise when the counterpart can no longer infer which behaviour will reduce danger. The difference is not semantic. Deterrence and compellence both depend on signalling. Deterrence attempts to convince another actor not to take an action; compellence attempts to force it to do something it would rather not do. In either case, the counterpart must form some belief about the relationship between its choices and your response. If that relationship becomes opaque, uncertainty may increase fear while decreasing control over what the fear produces.
The long argument over Taiwan shows why ambiguity cannot be judged independently of context. For decades, defenders of strategic ambiguity believed uncertainty over American intervention helped deter Beijing while discouraging Taipei from provocative unilateral action. Some analysts now argue that China’s military rise has changed the equation and that the same uncertainty could invite miscalculation rather than prevent it. The underlying lesson is not that clarity always beats ambiguity, but that ambiguity is only strategic when the beliefs it creates remain aligned with the behaviour one wants to produce.
Public coercion can make this harder. A leader who escalates in public may increase the credibility of a threat because backing down becomes politically costly. Yet that same mechanism can trap both sides. The coercer becomes invested in demonstrating resolve, while the target may become invested in demonstrating that it cannot be publicly humiliated. Bargaining space shrinks even as the pressure rises. Research on public commitments has long shown how attempts to create bargaining leverage can, under some conditions, increase the risk that negotiations break down.
The distinction can be put simply without pretending that diplomacy itself is simple. A target does not need certainty about what punishment will follow resistance. It needs sufficient certainty about what can prevent or end that punishment. Strategic ambiguity preserves some uncertainty around the first question, while strategic incoherence destroys confidence in the second. Beyond that point, unpredictability stops functioning primarily as a bargaining instrument and begins producing instability.
Uncertainty Cannot Be Exported for Free
A government using unpredictability tends to focus on the decisions it forces others to make. That perspective can hide a second balance sheet: the costs that return to the source. Economic policy makes those costs measurable. The Federal Reserve has found that uncertainty over trade policy can delay capital expenditure, discourage market entry and tighten credit, while its 2026 analysis of foreign direct investment warned that tariff uncertainty could undermine the very investment incentives tariffs were intended to create.
OECD and IMF research reached similar conclusions after the 2025 trade shocks: uncertainty affected investment, trade and corporate valuations independently of the eventual tariff burden. The evidence does not show that every tariff threat produces a measurable loss, or that every economy responds identically. It establishes a more limited but important point: the costs of policy instability are not confined to the country receiving the threat.
The same principle applies to diplomatic commitments, though it is harder to place on a spreadsheet. A promise has value because another actor believes it can plan around it. A security guarantee shapes military procurement only if the ally expects it to matter years from now. A trade agreement shapes factories and supply chains only if firms expect its basic terms to survive long enough to justify sunk investment. A threat can gain force from uncertainty, but promises lose force from the same source.
This creates a tension inside the foreign policy of any state that simultaneously wants maximum negotiating flexibility and maximum structural influence. The first rewards freedom to reverse, escalate or reinterpret. The second depends on other actors believing that some relationships will not be constantly reopened. A government can surprise its way through individual negotiations and still discover that partners have begun discounting the future value of its commitments.
Canada offers a contemporary example of adaptation rather than rupture. US tariffs and recurrent bilateral tensions have encouraged Ottawa to pursue deeper economic and strategic links with the European Union, including cooperation in defence, energy, critical minerals and technology. Canada is not abandoning the United States—its economic integration with its neighbour remains enormous—but reducing the concentration of dependence has become an explicit strategic objective. Australia, facing its own concerns about trade exposure, has publicly expressed interest in the same broader diversification logic.
This is what makes the long-term cost difficult to see. A partner does not need to retaliate dramatically for influence to erode. It can simply make the next port, factory, weapons contract, trade agreement or data centre slightly less dependent on you than the previous one was.
The Insurance Response
States under pressure rarely begin by constructing a rival world order. They buy insurance, and that insurance can take the form of larger weapons inventories, more domestic production, multiple energy suppliers, alternative export markets, redundant telecommunications infrastructure, strategic reserves or closer relations with additional powers. The purpose is not necessarily to leave an alliance or reject an economic system. It is to reduce the damage that one external decision can inflict.
Europe’s Anti-Coercion Instrument captures this logic unusually clearly. The EU defines economic coercion as a third country applying or threatening trade or investment measures in order to push the Union or a member state into a particular policy choice. The instrument is designed primarily for deterrence; Brussels explicitly says its ideal success would be never having to use it. Its existence tells potential coercers that Europe wants the capacity to impose costs if economic dependence is turned into political pressure.
The significance extends beyond Europe. The response to an uncertain environment is increasingly optionality: governments seek more than one supplier, more than one market, more than one security relationship or more than one technological route. Asian policymakers and investors have described their own strategies in similar terms, seeking resilience and flexibility amid US-China rivalry rather than treating geopolitical competition as a demand to choose a permanent camp. The result is not a neat transition from one bloc to another but a denser web of fallback arrangements.
Insurance also has limits. Reducing dependence can be expensive, inefficient or technically impossible in the short term. Companies that moved production out of China to reduce tariff and geopolitical exposure have in some cases moved operations back because China’s supplier ecosystems, infrastructure and skilled labour were difficult to reproduce elsewhere. Interdependence becomes leverage precisely because the relationship cannot be replaced by political declaration alone.
This prevents a simplistic conclusion that every act of coercion causes the target to escape. Often the target cannot. The more accurate claim is that coercion changes the target’s incentives. It places a political price on dependence that previously looked merely economic, and once that price is visible, governments and firms begin asking whether the efficiency gained from concentration is worth the vulnerability it creates. That question leads directly to the deeper mechanism at the heart of modern leverage: using a dependency reveals to the dependent actor exactly where its strategic exposure lies.
Leverage Teaches Escape
Globalisation did not eliminate state power; it reorganised it. Henry Farrell and Abraham Newman’s concept of weaponized interdependence explains how global networks in finance, information and production can become concentrated around critical hubs. States with jurisdiction over those hubs can sometimes use them to gather information or deny others access. What appears to be mutual economic interdependence can therefore contain a large asymmetry of coercive power.
This framework explains why the most consequential forms of modern pressure often operate without military force. Control over dollar clearing, advanced semiconductors, data infrastructure, export licences, insurance, critical minerals or a dominant market can create chokepoints that another actor cannot easily bypass. The power is structural: it exists before any government chooses to use it because firms and states have already organised their activities around the network. Every visible use of a chokepoint, however, teaches something to the actor being squeezed by identifying the dependency that carries political risk.
That does not mean the dependency disappears. Network effects can be exceptionally durable; alternative systems may be smaller, more expensive or less efficient, and attempts at rapid decoupling can damage the target as much as the coercer. This is why predictions that every sanctions dispute will end dollar dominance, or that every export control will create an independent technological ecosystem, routinely move faster than reality.
But power should not be measured only by whether an escape attempt succeeds immediately. It should also be measured by whether the pressure changes investment incentives over ten or twenty years. A country that starts subsidising domestic semiconductor capacity, building LNG terminals, diversifying reserves or signing additional trade agreements may remain dependent on the old system while steadily reducing the share of its future that depends on it.
This is the mechanism that short-term bargaining analysis tends to miss. Successful coercion confirms that the leverage exists. By confirming it, the coercer may provide the target with the strongest possible evidence that the dependence is dangerous. Leverage teaches escape—not always successfully, not cheaply and not quickly, but the more often an essential relationship is converted into a pressure point, the harder it becomes to persuade the dependent actor that preserving that dependence is merely efficient rather than strategically reckless. The greatest users of coercive leverage therefore face a problem weaker states do not: they must decide how much of an advantage they are willing to spend.
Predictability Is Also a Form of Power
Great powers are often admired for the options they possess. They can impose sanctions, move troops, deny technology, offer security guarantees, open markets, close markets, recognise governments, withhold recognition or simply leave rivals uncertain about which of those actions will come next. Optionality is power because it prevents others from dictating your choices. But leadership requires a second kind of power that is almost the inverse of optionality: the ability to make other actors confident enough in your future behaviour that they organise their own future around you.
The United States’ post-war influence cannot be explained by military capability alone. Allies bought American weapons, hosted American forces and structured security policy around American commitments because those commitments were expected to possess continuity beyond one meeting. Companies built supply chains around access to the American market. Governments accumulated dollar assets partly because the financial architecture was deep, liquid and institutionally durable. None of those relationships was free of coercion or asymmetry, but their strategic value depended heavily on predictability.
This does not require a great power to become passive. A completely predictable coercer can be exploited, and diplomacy sometimes benefits from leaving adversaries uncertain about thresholds or responses. The mistake is to assume that because some uncertainty produces leverage, more uncertainty must produce more leverage.
A state’s reputation for unpredictability affects threats and promises simultaneously. The threat may become more frightening because the target cannot confidently dismiss escalation. The promise may become less valuable because the target cannot confidently build on it. Foreign policy that focuses only on the first effect can mistake immediate movement for durable influence.
The same trade-off appears in alliances. Pressure can make allies spend more, contribute more or concede more. It can also persuade them that capabilities once provided collectively should now be duplicated nationally or regionally. Both outcomes may occur at the same time. The coercer can therefore point to a successful concession as evidence that the tactic worked while overlooking the insurance purchased because the tactic worked.
This is why reliability should not be confused with softness. Predictability can lower the cost of coalition building, increase the value of guarantees, encourage investment and make other governments willing to accept dependence because they believe the relationship will remain governed by intelligible limits. Those are forms of power precisely because they change other actors’ behaviour without a new threat being required every morning.
The strategic choice is not between being perfectly predictable and permanently surprising. Serious statecraft requires both flexibility and credibility, risk and restraint, threats and assurances. The harder judgment is deciding which relationships gain value from uncertainty and which are valuable because uncertainty has been reduced. Unpredictability can win a negotiation by forcing the other side to insure against what you might do, but used repeatedly it can make that insurance permanent.
If the target stops believing that compliance will end the pressure, the coercer may retain the ability to inflict costs while losing the ability to convert those costs into agreement. At that point, the appearance of maximum leverage conceals a quieter loss of control, because the strongest position is not simply to make others fear that you may change the terms tomorrow. It is to possess enough power that you could change them, while maintaining enough credibility that partners still choose to build their tomorrow around you.